THE PLOT BUYER’S GUIDE · 2026
How to Get a Loan for Plots in Gurgaon: Check Eligibility, Interest Rates & How to Apply
Planning to buy a plot in Gurgaon or Sohna? Learn how plot loans work, how much you may borrow, what documents are needed and how to apply.
Understand your budget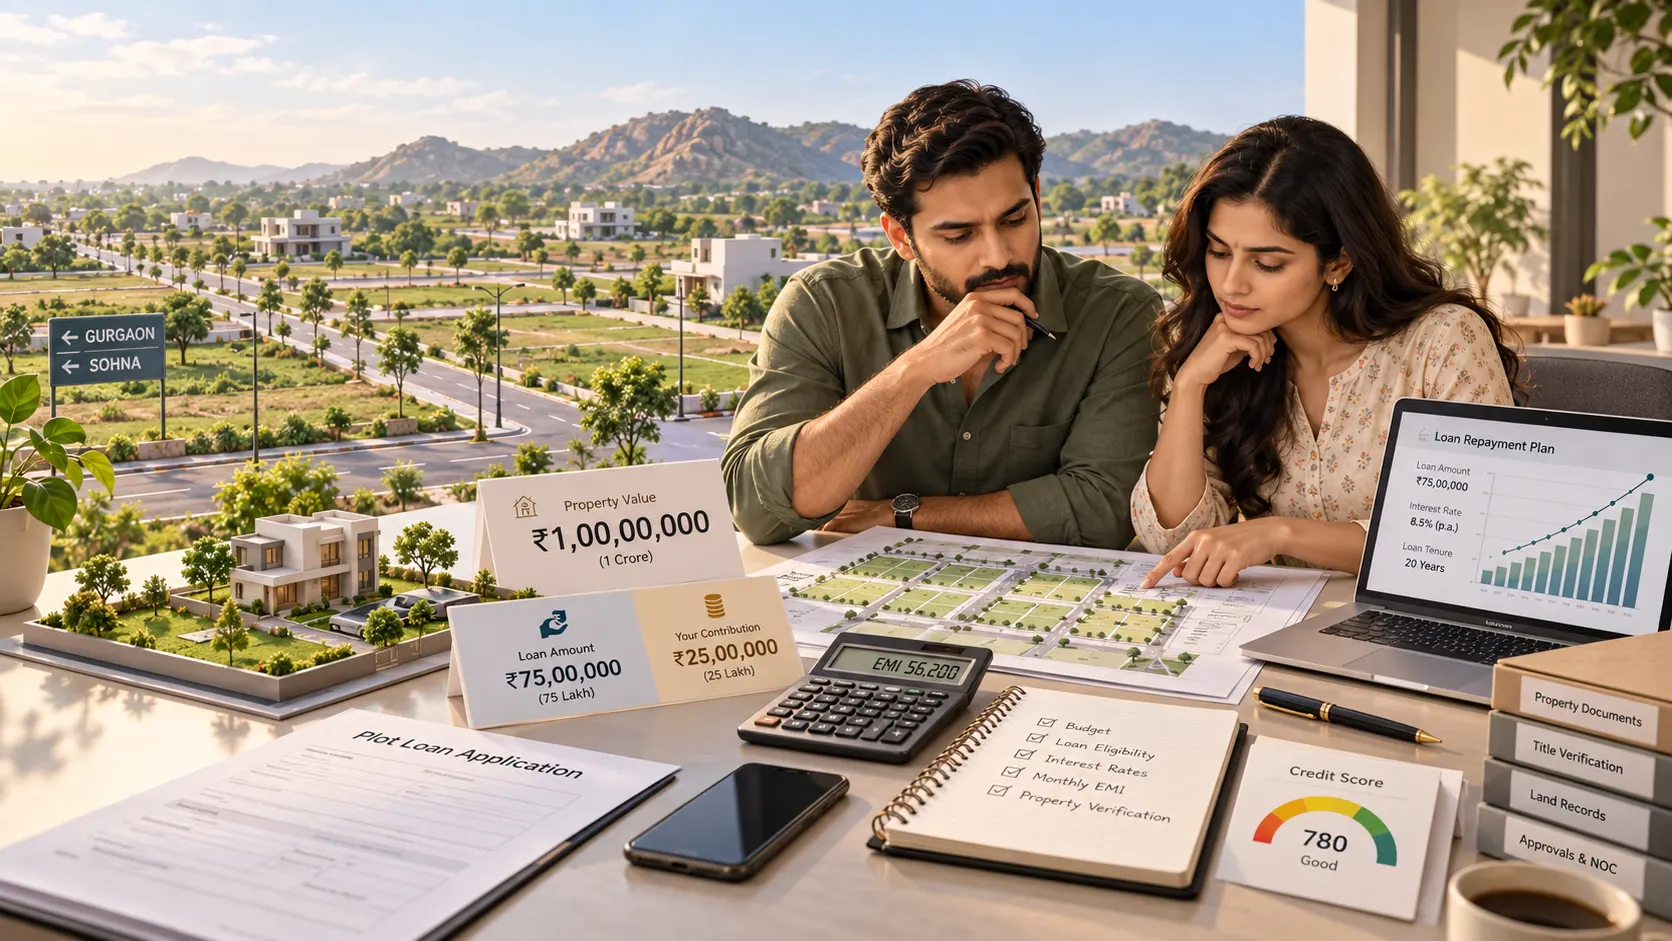
Suppose you have shortlisted a residential plot in Gurgaon or Sohna priced at ₹1 crore or ₹1.5 crore, but you do not want to pay the full amount from your savings. In that case, a plot loan in Gurgaon may help finance part of the purchase.
Banks and housing finance companies can offer loans for eligible residential plots. However, getting a loan depends on two things: your ability to repay it and whether the selected plot meets the lender’s property requirements.
Before applying, you should understand how much loan you may get, how much down payment you need, which documents the bank will check and how the approval process works.
This guide explains plot loan eligibility, interest rates, documents, property checks, EMI and the complete application process in simple terms.
Can You Get a Bank Loan to Buy a Residential Plot in Gurgaon?
Yes, banks and housing finance companies can provide loans for purchase of eligible residential plot in Gurgaon or Sohna. But loan approvals depend both on the buyer and the property. The lender will check your income, credit history, existing EMIs and whether the selected plot meets its lending rules.
A plot loan in Gurgaon is primarily used when you want to buy residential land. If you plan to build a house later, some lenders may have a separate plot-plus-construction loan. The exact terms can vary, so it’s important to know which type of loan fits your plan.
How Is a Plot Loan Different From a Home Loan?
You can take a home loan to buy a ready home or an apartment which is under construction or to build a house on a plot you own. A plot loan is primarily used for purchasing residential land.
Since no house has been built on the plot, lenders typically pay special attention to location of the plot, its residential use, ownership documents and project approvals. Some plot loan products may also require the purchaser to commence or complete construction within a specified period. This condition is not the same with each lender, so it should be checked before signing the loan agreement.
Plot Purchase Loan vs Loan Against Property
A plot purchase loan helps you buy a residential plot that you do not currently own. The loan amount is used toward the purchase of that land, subject to the lender's approval.
A loan against property works differently. In this case, you already own a house, commercial property or other eligible property and use it as security to borrow money.
So, if your main goal is to buy a residential plot in Gurgaon or Sohna, a plot purchase loan is usually the relevant option to explore.
Which Residential Plots in Gurgaon and Sohna Can Banks Finance?
Not every plot being sold as residential land will qualify for bank finance. Before approving a plot loan in Sohna or Gurgaon, the lender checks whether the property meets its lending rules. The plot's legal use, ownership, project approvals and location can all affect the final decision.
For example, LIC Housing Finance currently states that its plot-purchase loan is meant for residential plots purchased from government bodies, development authorities or approved layouts. This shows why the legal status and approved layout of the property matter when a lender evaluates a plot for financing.
This is important because a buyer may have good income and a strong credit profile, but the loan can still be delayed or rejected if the selected plot does not meet the lender's property requirements. If you are planning to pay a booking amount soon, it is better to check the plot's loan eligibility first rather than discover a problem after making a large payment.
You can also review the lender's official plot-loan criteria directly on the LIC Housing Finance Plot Loan page before applying.
Can You Get a Loan for DDJAY and Gated Community Plots?
A DDJAY plot or a plot inside a gated community may qualify for bank finance, but the project name or category alone is not enough. DDJAY stands for Deen Dayal Jan Awas Yojana, under which licensed plotted residential colonies are developed in Haryana.
The lender will still review the exact project and plot before giving final approval. The same applies to resale plots. A resale property can also qualify if its ownership history, approvals and other documents meet the lender's requirements.
If you have already shortlisted a plot, ask the lender whether it can finance that specific project before paying a large non-refundable amount. This small check can save you from arranging more money later if the bank sanctions less than expected or refuses the property.
What Plot Approvals and Documents Does the Bank Check?
For a plotted project, lenders may review the ownership records, approved layout, development licence and other permissions linked to the property. If the project is required to be registered with Haryana RERA, its registration details should also be checked.
For example, HDFC Bank provides information about property-related documents and checks that may apply during a home or plot loan process. This is why buyers should confirm whether the lender accepts the specific plot and whether the required property documents are complete before applying.
However, RERA registration alone does not guarantee that a bank will approve the loan. RERA registration and bank finance are separate checks. A project may be registered with RERA but still need to meet the lender's legal, technical and valuation requirements.
For a first-time buyer, the practical order is simple: check your personal loan eligibility, shortlist the plot and then confirm whether the lender accepts that exact property. Doing this before making a major payment gives you a clearer idea of how much money you may need from your own savings.
Choosing a location? Read our guide to the best areas to buy plots in Gurgaon and compare DDJAY plots in Sohna.
How Much Plot Loan Can You Get in Gurgaon?
The amount you can borrow for a residential plot depends on two things: how much the lender is willing to finance against the property and how much loan your income can support. This means a ₹1 crore plot does not automatically qualify you for a ₹75 lakh loan.
How Much Down Payment Do You Need?
Suppose you are buying a residential plot for ₹1 crore. If a lender agrees to finance 75% of the accepted property value, the calculation would look like this:
| Details | Amount |
|---|---|
| Plot price | ₹1 crore |
| Loan at 75% | ₹75 lakh |
| Your contribution | ₹25 lakh |
In this example, you need at least ₹25 lakh from your own funds. Stamp duty, registration fees and other applicable charges would normally need a separate budget.
The 75% figure is only an example. Some lenders may finance less depending on the property, your income, existing EMIs and their internal loan rules.
How Does the Bank Decide the Plot's Value?
The bank does not always use the seller's asking price as the final value. It may arrange a property valuation before deciding the loan amount.
For example, suppose the seller asks ₹1 crore, but the lender values the plot at ₹90 lakh. If the lender finances 75% of that accepted value, the loan would be about ₹67.5 lakh. You would then need to arrange the remaining ₹32.5 lakh yourself, apart from registration and other costs.
This is why it is useful to understand the likely loan amount before committing a large booking payment. Your final plot loan amount will depend on both the property's accepted value and your repayment capacity.
Keep purchase costs separate: see plot registry charges in Gurgaon.
Who Can Apply for a Plot Loan in Gurgaon?
A salaried employee, self-employed professional or business owner may apply for a plot loan in Gurgaon if they can show regular income and meet the lender's eligibility rules. The bank mainly wants to understand whether you can comfortably repay the loan without putting too much pressure on your monthly budget.
Income, CIBIL Score and Existing EMIs
Your monthly income is important, but banks do not look at salary alone. They also check your existing EMIs, credit-card payments, other loans and repayment history.
Your CIBIL score is a numerical summary of your credit history. A stronger credit history can support your application, but no particular score guarantees approval.
For example, imagine two buyers earning ₹1.5 lakh per month. Buyer A has no major existing loan, while Buyer B already pays ₹45,000 every month toward a personal loan. Even with the same salary, Buyer A may qualify for a higher plot loan because more monthly income is available for a new EMI.
Plot Loan Eligibility for Salaried and Self-Employed Buyers
Salaried buyers are usually asked to provide salary slips, bank statements and tax documents. Self-employed buyers may need to show ITRs, business income records and bank statements.
For both groups, income stability matters. A lender may also consider your age, existing debts and the loan tenure you are requesting.
So, plot loan eligibility depends on the complete financial picture, not just your monthly income. Before choosing a plot, it is useful to check how much EMI your current income can comfortably support.
What Documents Do You Need for a Plot Loan?
Before applying for a plot loan, it helps to keep both your personal documents and the property papers ready. The bank checks these separately. Your documents show whether you can repay the loan, while the property documents help the lender decide whether the selected plot is suitable for financing.
Personal and Income Documents
As a buyer, you usually need to provide basic identity and income proof. This may include your PAN card, Aadhaar or other address proof, recent bank statements and photographs.
If you are salaried, the lender may ask for recent salary slips, Form 16 and employment details. If you are self-employed, you may need to provide income-tax returns, business records and bank statements showing your income.
The exact list can vary from one lender to another, so it is useful to check the requirements before submitting the application.
Plot Ownership and Approval Documents
The property documents normally come from the seller or developer. These may include ownership records, the proposed sale agreement, approved layout plan, development licence and other permissions that apply to the project.
For resale plots, the lender may also ask for earlier sale deeds or documents showing the ownership history of the property.
| Buyer Documents | Property Documents |
|---|---|
| PAN card | Ownership or title documents |
| Identity and address proof | Sale agreement or allotment letter |
| Recent bank statements | Approved layout plan |
| Salary slips or ITR | Development licence, where applicable |
| Form 16 or business income proof | RERA details, where applicable |
| Existing loan details | Previous sale deeds for resale plots |
Keeping these plot loan documents ready can make the application process smoother. However, having all the papers does not guarantee approval. The lender will still verify both your financial position and the property before issuing the final loan sanction.
For a closer look at title records, read how to verify plot ownership documents in Gurgaon.
How to Apply for a Plot Loan in Gurgaon: Step-by-Step Process
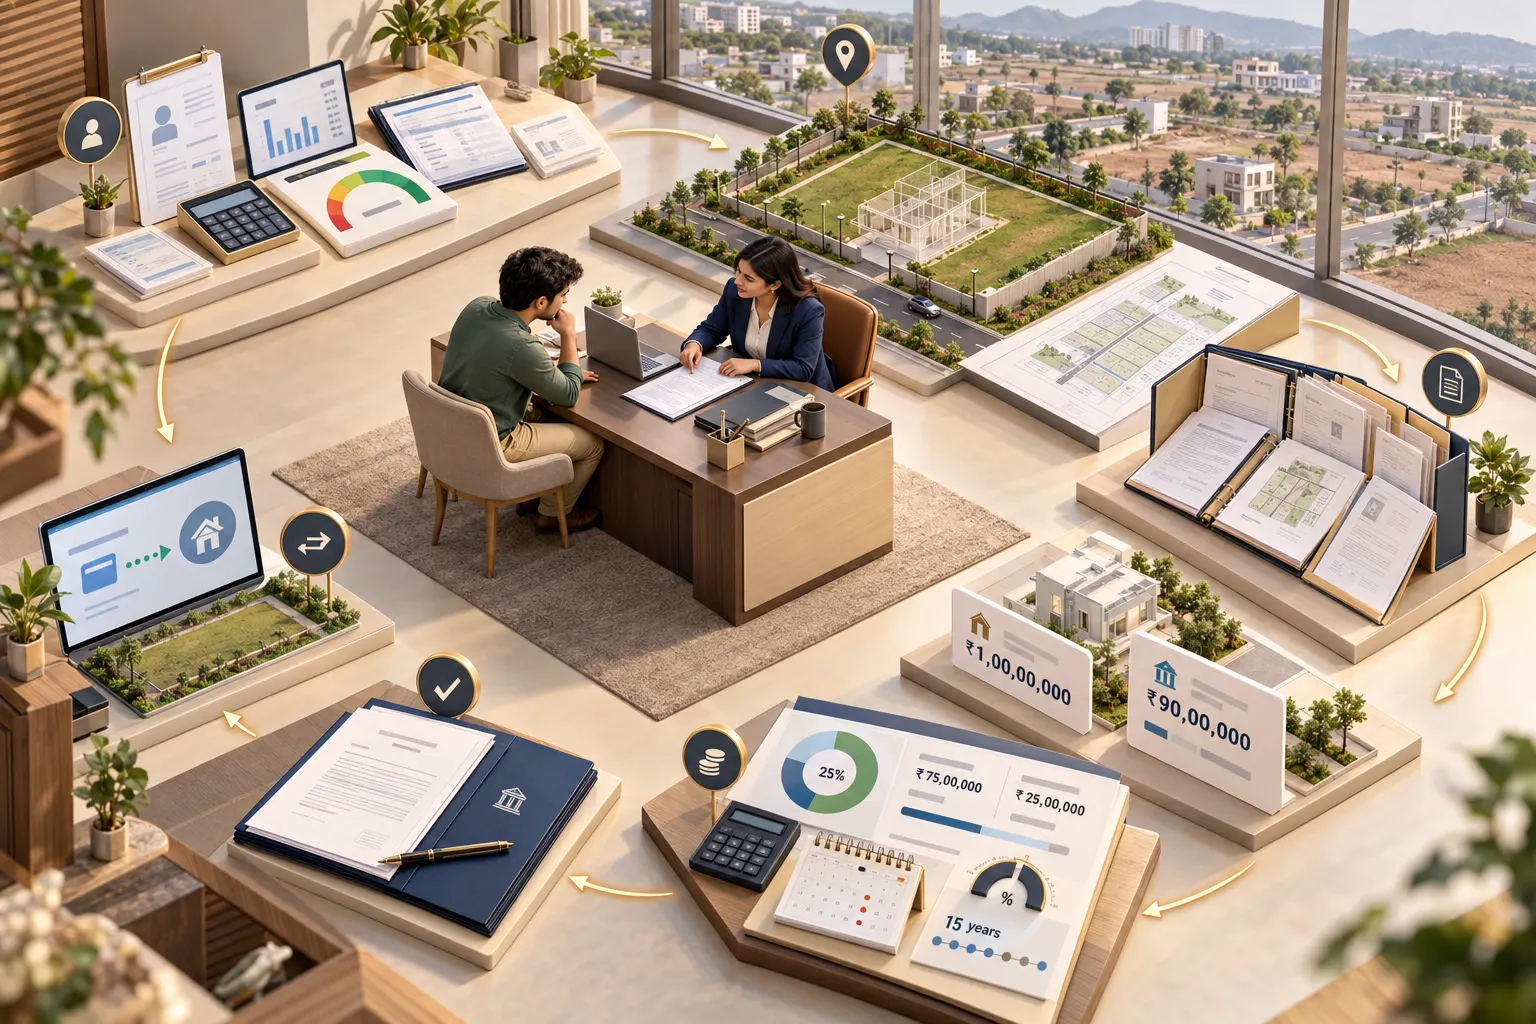
If you are applying for a plot loan for the first time, the process becomes easier when you follow it in the right order. The bank first checks your repayment ability and then checks whether the selected plot is acceptable for financing.
From Loan Eligibility Check to Final Approval
Start by checking how much loan your income may support. At this stage, the lender may review your salary or business income, existing EMIs and credit history. This gives you an initial idea of your borrowing capacity, but it is not the final loan approval.
Once you know your approximate eligibility, shortlist the residential plot and collect the required property documents from the seller or developer.
The usual plot loan process looks like this:
- Check your approximate loan eligibility.
- Shortlist a residential plot within your budget.
- Ask the lender whether that type of property can be financed.
- Collect your income and property documents.
- Submit the loan application.
- The lender checks your financial details and property papers.
- The property may be inspected and valued.
- If everything is acceptable, the lender issues a sanction letter.
- You arrange your required contribution or down payment.
- Registration and loan disbursement are completed according to the lender's conditions.
A sanction letter is the lender's written approval showing the loan amount, interest rate, tenure and important conditions. It should be read carefully before you accept the loan.
What Happens During Property Verification and Loan Disbursement?
Once you have submitted your application, the lender will typically verify property documents, such as the ownership documents, approved layout, etc. It might also set up an evaluation to determine the worth of the plot for lending.
This is the reason for the difference between initial eligibility and final approval. While you might meet the requirements on a financial level, if the property you choose does not satisfy the lender, then you might not even be eligible for the loan.
If you have to pay a lump sum or a non-refundable booking fee, inquire with the seller or developer regarding cancellation and refund policies. Meanwhile, check with the lender if the particular plot is eligible for financing.
If the conditions in the sanction letter are fulfilled, then once the contributions are paid and the formalities of registration are completed, the lender can release the sanctioned amount to the seller/ developer.
Following this order helps you understand your financing before committing a large amount of your own money.
What Are Plot Loan Interest Rates, EMIs and Other Charges?
There is no single plot loan interest rate for every buyer in 2026. Your rate depends on the lender, loan amount, credit profile and property. Even a small difference in the interest rate can affect your monthly EMI and total repayment over 10–15 years.
Fixed and floating interest rates are also available. A fixed rate stays unchanged for the agreed fixed-rate period, while a floating rate can change with the lender's benchmark. Before opting for a choice, find out the effect of a rate change on your EMI or loan tenure.
How Is Your Monthly EMI Calculated?
EMI means Equated Monthly Instalment. It is the amount you pay every month towards both the loan amount and interest.
Suppose you take a ₹75 lakh plot loan for 15 years. For this example only, assume an interest rate of 8.5% per year.
| Loan Detail | Illustrative Amount |
|---|---|
| Loan amount | ₹75 lakh |
| Assumed interest rate | 8.5% |
| Loan tenure | 15 years |
| Approx. monthly EMI | ₹73,855 |
| Approx. total interest | ₹57.94 lakh |
This is only an example, not a current lender quotation. A higher or lower interest rate will change both the EMI and total interest you pay.
What Extra Charges Should You Budget For?
Your EMI is not the only cost of taking a plot loan. Depending on the lender and transaction, you may also pay processing fees, property valuation or legal-check charges, mortgage-related costs and applicable taxes. Separately, the plot purchase itself can involve stamp duty and registration charges.
Before accepting a loan, ask for the lender's Key Facts Statement (KFS). It shows important loan terms in a standard format. Also check the Annual Percentage Rate (APR), which gives a broader view of borrowing cost by including the interest rate and applicable lender charges.
Comparing the KFS, APR, repayment schedule and total amount payable gives you a clearer picture than comparing only the advertised interest rate.
Do You Need to Build a House After Taking a Plot Loan?
Not every plot loan requires you to start building a house immediately. The condition depends on the lender and the type of loan you choose. Some lenders offer a standalone plot purchase loan, while others offer a combined plot-and-construction loan with a fixed construction timeline.
This difference is important if you are buying a plot now but plan to build several years later.
What Happens If You Don't Build Within the Required Time?
A standalone plot loan primarily finances an eligible plot. A composite loan combines the purchase of land with the construction of a house.
Some composite loans set a construction deadline. For example, LIC Housing Finance states that applicants for its composite plot-and-construction loan should intend to complete construction within three years of buying the plot.
If you do not build within the required period, the consequences depend on your loan agreement. Ask the lender to explain the applicable conditions before you sign.
This is particularly important if you are purchasing the plot primarily as a holding for 5 or 10 years. Prior to investing in a plot loan, enquire if there are any construction timelines, if the interest rate could vary if the investor doesn't build, and if a standalone plot loan is more suited to their plan.
The essential thing is to know what you are going to use a loan for – not just what you can afford the lender to finance.
Planning to build soon? Check our ready-to-build plots in Sohna guide.
Why Might a Bank Reject Your Plot Loan Application?
A bank can reject a plot loan even when you have a regular income and have already selected a property. Loan approval depends on both your financial position and the plot itself, so a problem on either side can affect the decision.
Problems With Income, Credit Score or Plot Documents
One common reason is limited repayment capacity. If a large part of your monthly income is already going towards existing EMIs, the lender may feel that another loan would put too much pressure on your budget.
Your credit history also matters. Missed payments, high credit use or recent loan defaults can make the lender more cautious, although there is no single CIBIL score that guarantees approval.
The property can also create issues. Incomplete ownership papers, unclear title, missing approvals, disputed land or documents that do not meet the lender's requirements may lead to rejection or a lower loan amount.
Before applying, check a few basics:
- Keep income and bank records updated.
- Review your existing EMIs.
- Check your credit report for errors.
- Collect complete plot documents.
- Confirm the approved layout and relevant permissions.
- Ask the lender whether the specific plot is eligible for finance.
These checks cannot guarantee approval, but they can help reduce avoidable plot loan rejection reasons and give you a clearer idea of your eligibility before you make a major payment.
Frequently Asked Questions About Plot Loans in Gurgaon
Can I Get a Plot Loan Before Finalising a Property?
You may be able to get an initial loan eligibility estimate before choosing a plot. However, final approval usually comes only after the lender checks the specific property, its documents and valuation. Treat initial eligibility as a budget guide, not a guarantee of funding.
Can Two Family Members Apply for a Plot Loan Together?
Many lenders allow joint applications, especially with an earning family member. Adding a co-applicant may improve loan eligibility because both incomes can be considered. However, rules about relationships, ownership and whose income can be counted vary by lender, so check these conditions before applying.
Can I Get a Loan for a Resale Plot in Gurgaon?
A resale residential plot may qualify for financing if the lender accepts the property and its documents. The bank may check the seller's ownership, previous sale records, approved layout and other applicable permissions before deciding whether the plot can be financed.
Do Banks Offer Plot Loans for NRIs?
Some lenders offer plot loans to NRIs, subject to their eligibility and property rules. For example, LIC Housing Finance currently lists resident and non-resident individuals as eligible applicants for its plot-loan products. Other lenders may have different income, documentation and construction requirements.
Are There Tax Benefits on a Plot Purchase Loan?
Buying vacant land by itself does not automatically give you the same tax deductions associated with a completed house. Income-tax provisions generally relate housing-loan interest deductions to the purchase or construction of house property. Tax treatment can change after construction, so check the applicable tax rules for your situation.
Can I Repay My Plot Loan Before the End of the Tenure?
Yes, lenders generally allow part-prepayment or full repayment before the original tenure ends. Charges depend on the loan type and lender. RBI rules restrict prepayment penalties on qualifying floating-rate loans to individual borrowers, but you should still check the exact terms in your sanction letter.
What Should You Check Before Applying for a Plot Loan?
Before applying, look at three things together: how much EMI your income can comfortably support, how much money you can contribute from your savings and whether the selected plot meets the lender's property requirements.
Do not choose a plot only because a lender has given you an initial eligibility amount. Confirm the property documents, likely loan amount, interest rate, additional charges and construction conditions before making a major payment. This gives you a clearer picture of the real cost and responsibilities of taking a plot loan.
The 75% financing ratio and 8.5% interest rate are assumptions, not current offers. The EMI example uses ₹75 lakh over 15 years; figures within the supplied illustrations may use different assumptions. Confirm rates, fees and construction conditions with your lender.
YOUR NEXT STEP
Find a plot that fits your plans.
Explore AQVA The Reserve in Sohna and speak with our team about the project and available plot details.
CONTINUE READING
Make your next decision with clarity.
Where should you buy a plot in Gurgaon?
Read guide
Budget for plot registry charges
Read guide